E.SUN Bank and IBM build an AI governance system for safe AI adoption in banking
E.SUN Bank and IBM are launching an AI governance project for the banking environment. The goal isn't simply to add more models. It's to define the rules for using them: where AI is allowed, how its decisions get checked, and who owns the risk. As AI spreads across anti-fraud, credit scoring, and customer support, this kind of framework is becoming core infrastructure.
AI-processed from AI News; edited by Hamidun News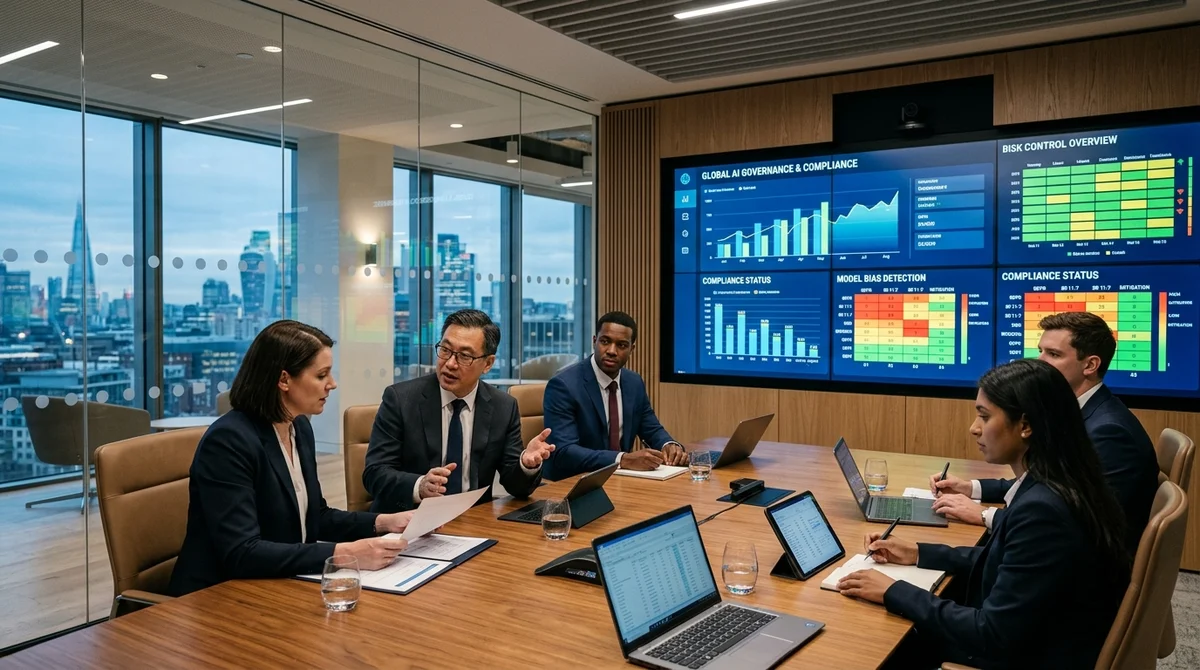
E.SUN Bank is working with IBM on an AI governance framework that will define exactly how the bank can use artificial intelligence internally. For the financial sector, this is no longer an experiment. It's an attempt to turn the rapid growth of AI tools into a system that can be managed and audited.
Why control is needed
Banks no longer use AI only in pilots. It now runs in day-to-day operations: screening suspicious transactions, assessing loan applications, and handling customer requests. The more of these use cases there are, the higher the cost of a mistake. If a model rejects an application without a clear explanation, misses fraud, or gives an employee bad guidance, the problem quickly stops being technical and becomes a regulatory and reputational one. That's why the question is shifting from "where do we deploy AI" to "how do we keep it under control."
The E.SUN Bank–IBM partnership reflects exactly that shift. Financial institutions need more than a model with good metrics. They also need a set of rules covering its entire lifecycle, from data selection and testing to post-launch monitoring. In banking, it's not enough to prove a system works on average. The bank has to know when it might fail, who is allowed to change its parameters, how decisions are logged, and when a human must step in.
What the framework will include
The brief project description doesn't disclose details, but AI governance typically comes down to several mandatory layers of control. A bank must not only permit AI use but also set the boundaries of that use in advance. This matters most where decisions involve money, personal data, and customers' access to services. In practice, such a framework usually covers policy, approval processes, quality control, and a division of responsibility between the business, IT, and compliance.
- criteria for which products AI is acceptable in, and where only a human should decide
- requirements for data quality, model testing, and bias checks
- decision audits, change logging, and a clear chain of accountability
- post-launch monitoring procedures, including triggers to review or shut down a model
For IBM, projects like this fit naturally into its enterprise agenda around trustworthy AI and risk management. For E.SUN Bank, the point isn't to slow down the rollout of new tools but the opposite: to make it predictable. With rules written down in advance, the bank can more easily scale AI across departments: anti-fraud, scoring, support, and internal operations. Without a shared framework, each team invents its own process, and inconsistencies, duplicated controls, and legal risks pile up along with it.
Why banks are in a hurry
The financial sector has particular reasons to move. Banks operate under strict oversight, hold sensitive data, and make decisions that directly affect customers. So even a useful AI system can't just be dropped into a process in the hope that it will behave like ordinary software. A model changes along with its data, can degrade over time, and sometimes behaves unpredictably on rare edge cases. The more the market experiments with generative AI and customer service automation, the stronger the demand for unified control rules.
That points to a broader lesson for the industry: the next wave of competition will be fought not only over model quality but over how mature the governance around those models is. The winners will be banks that can speed up their processes while proving to regulators, auditors, and customers that AI is used transparently. In that sense, governance is becoming as essential a part of infrastructure as cybersecurity, access management, or redundancy for critical systems. Without it, AI remains a collection of scattered experiments.
What it means
The E.SUN Bank and IBM project shows that for banks, the main question is no longer "do we need AI" but "what rules does it run by." If frameworks like this become standard, the market will move faster from isolated pilots to broad, but more tightly controlled, adoption of AI in financial services.
- Oct 31, 2026Author puts his script before an AI jury: the verdict cost 850 thousand tokens
- Oct 29, 2026OvisOCR3: an 0.8B-parameter model that reads documents better than specialized systems
- Oct 29, 2026Tencent releases Youtu-Parsing-Omni: one model parses documents, audio and video
- Oct 28, 2026Liquid AI releases LFM2.5-24B-A2B: an agent model with 2B active parameters
Key Questions Answered
Why control is needed?
Banks no longer use AI only in pilots. It now runs in day-to-day operations: screening suspicious transactions, assessing loan applications, and handling customer requests. The more of these use cases there are, the higher the cost of a mistake. If a model rejects an application without a clear explanation, misses fraud, or gives an employee bad guidance, the problem quickly stops being technical and becomes a regulatory and reputational one. That's why the question is shifting from "where do we deploy AI" to "how do we keep it under control." The E.SUN Bank–IBM partnership
What the framework will include?
The brief project description doesn't disclose details, but AI governance typically comes down to several mandatory layers of control. A bank must not only permit AI use but also set the boundaries of that use in advance. This matters most where decisions involve money, personal data, and customers' access to services. In practice, such a framework usually covers policy, approval processes, quality control, and a division of responsibility between the business, IT, and compliance. criteria for which products AI is acceptable in, and where only a human should decide requirem
Why banks are in a hurry?
The financial sector has particular reasons to move. Banks operate under strict oversight, hold sensitive data, and make decisions that directly affect customers. So even a useful AI system can't just be dropped into a process in the hope that it will behave like ordinary software. A model changes along with its data, can degrade over time, and sometimes behaves unpredictably on rare edge cases. The more the market experiments with generative AI and customer service automation, the stronger the demand for unified control rules. That points to a broader lesson for the indust
Test Frontier LLMs & Autonomous Agents in One Workspace
Run Claude Opus 5.5, GPT-6, Gemini 3.1, and DeepSeek side-by-side in Nomad AI (nomadnet.ai) — unified model routing, deep research, and multimodal workflows under one subscription.
The AI world, distilled — once a week
Seven stories that actually mattered, hand-picked. No noise, no reposts, no press releases.
Done! Check your inbox for a confirmation.