Meta shares slide after it raises 2026 AI and data center spending forecast
Meta shares fell sharply after the company raised its 2026 capital expenditure forecast to $125–145 billion. The new range came in above analyst expectations and deepened fears that record spending on AI, servers and data centers will grow faster than any clear return for investors. Rising component prices and infrastructure expansion add further pressure. *Meta has been designated an extremist organization and is banned in Russia.
AI-processed from Bloomberg Tech; edited by Hamidun News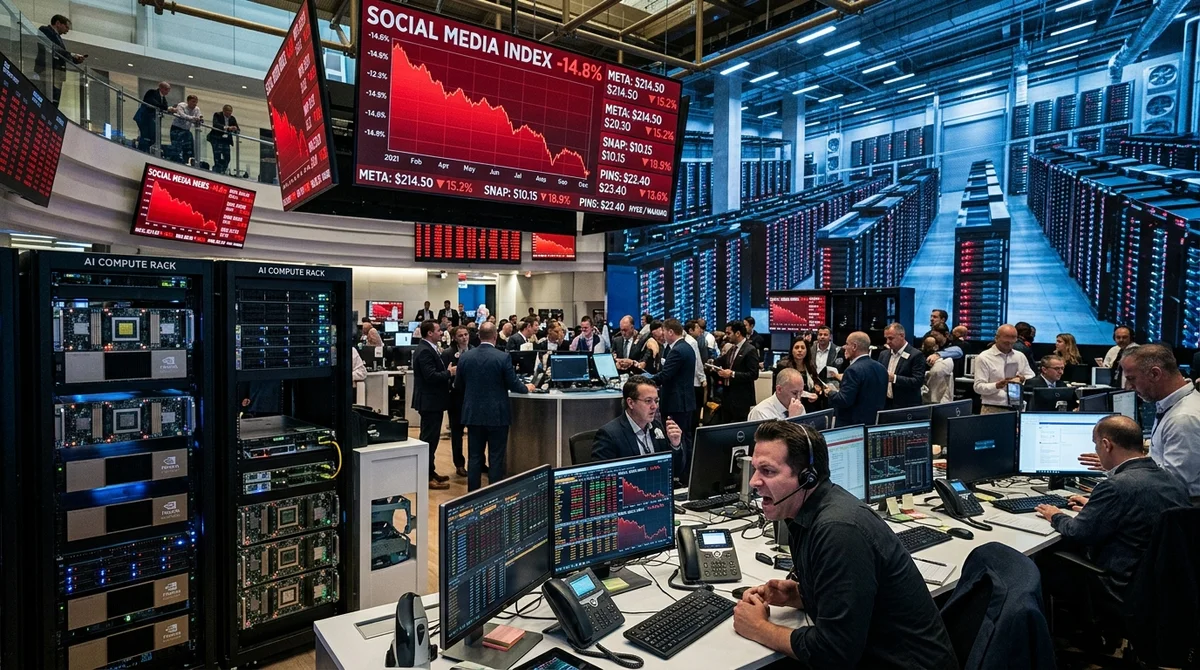
Meta shares dropped sharply after the company raised its 2026 capital expenditure forecast to $125–145 billion. The market read it as a signal: the race for AI leadership is getting even more expensive, and the payoff for investors is still unclear.
Why the stock fell
What unsettled investors was not Meta's desire to spend more on artificial intelligence, but the scale of the revision. The company now expects capital expenditure of $125 billion to $145 billion for the year. That is noticeably above analyst expectations and roughly 7.4% higher than the previous guidance.
For the market, this is a painful signal. Meta is already among the companies spending record sums on AI: on training models, compute infrastructure and building data centers. Such spending is easy to justify as a growth strategy, but it is much harder to show when exactly it will start turning into profit. So any budget expansion quickly revives the old question: will this bet pay off?
The reaction shows that investors have become noticeably stricter about AI spending. If a company raises its cost forecast faster than it explains future monetization, the stock comes under pressure immediately. For Meta this is especially sensitive, because it has to defend a strong advertising business while financing an extremely expensive technological push.
What is driving the spending
Chief Financial Officer Susan Li gave several reasons for the revised forecast. It is not only about the scale of Meta's ambitions, but also about the rising cost of the infrastructure without which modern AI simply does not work.
The company is facing "higher component prices" and additional data
center costs.
Behind this short phrasing lies fairly clear economics of the AI boom:
- accelerators and server components are getting more expensive amid huge demand;
- building and expanding data centers requires more capital than previously budgeted;
- launching and training large models increases the need for electricity, cooling and network infrastructure;
- competition among tech giants pushes companies to reserve capacity in advance, even when there is no immediate payoff.
That is why the revision looks less like a one-off accounting adjustment and more like a sign of a costlier phase of the AI race. The more aggressively Meta adds capacity, the higher the risk that costs will grow faster than the advertising and product revenue the market is used to seeing from the company.
A bet on the long game
From Meta's own perspective, the logic is clear. To stay among the AI leaders, the company has to invest not only in models but also in basic infrastructure: compute, data storage and physical sites. The problem is that the stock market does not price strategic intent; it prices the balance between spending today and results tomorrow.
Right now, investors see only the first half of the equation. They understand that Meta has to compete for chips, capacity and talent, but they are not yet getting a clear enough answer on when these investments will turn into new cash flows of comparable scale. Against this backdrop, even a strong operating business does not always shield the stock from a sharp reaction: the bigger the AI check, the higher the bar for proving efficiency.
On the other hand, the risk of underinvesting is also high for Meta. If demand for AI infrastructure keeps growing, falling behind on capacity could cost the company no less than overspending. Management appears to be choosing the more aggressive scenario: spend more now so as not to play catch-up later in an even more expensive market.
What this means
The reaction to Meta's report shows that the market no longer applauds every AI expense by default. Investors now want not just ambition but a clear path to payback: whoever can prove returns on the infrastructure race will win not only technologically, but on the stock market as well.
*Meta has been designated an extremist organization and is banned in Russia.
- Nov 1, 2026MoneyGate safety layer blocked all 42 fraudulent requests to local AI models
- Oct 31, 2026Open-source LLM gateway KTMS 1.0 plugs your own GPUs into the cloud and survives outages
- Oct 31, 202622B-Parameter LTX-2.5 Runs on a 10 GB RTX 3080, but Takes 5 Minutes per Shot
- Oct 29, 2026T-Tech Introduces LIMe, a Method That Trains Language Models With 15% Less Compute
Key Questions Answered
Why the stock fell?
What unsettled investors was not Meta's desire to spend more on artificial intelligence, but the scale of the revision. The company now expects capital expenditure of $125 billion to $145 billion for the year. That is noticeably above analyst expectations and roughly 7.4% higher than the previous guidance. For the market, this is a painful signal. Meta is already among the companies spending record sums on AI: on training models, compute infrastructure and building data centers. Such spending is easy to justify as a growth strategy, but it is much harder to show when exactl
What is driving the spending?
Chief Financial Officer Susan Li gave several reasons for the revised forecast. It is not only about the scale of Meta's ambitions, but also about the rising cost of the infrastructure without which modern AI simply does not work. The company is facing "higher component prices" and additional data center costs. Behind this short phrasing lies fairly clear economics of the AI boom: accelerators and server components are getting more expensive amid huge demand; building and expanding data centers requires more capital than previously budgeted; launching and training large mod
What are the key details on A bet on the long game?
From Meta's own perspective, the logic is clear. To stay among the AI leaders, the company has to invest not only in models but also in basic infrastructure: compute, data storage and physical sites. The problem is that the stock market does not price strategic intent; it prices the balance between spending today and results tomorrow. Right now, investors see only the first half of the equation. They understand that Meta has to compete for chips, capacity and talent, but they are not yet getting a clear enough answer on when these investments will turn into new cash flows o
Test Frontier LLMs & Autonomous Agents in One Workspace
Run Claude Opus 5.5, GPT-6, Gemini 3.1, and DeepSeek side-by-side in Nomad AI (nomadnet.ai) — unified model routing, deep research, and multimodal workflows under one subscription.
The AI world, distilled — once a week
Seven stories that actually mattered, hand-picked. No noise, no reposts, no press releases.
Done! Check your inbox for a confirmation.