UK regulator FCA floats direct regulation of ChatGPT, Claude and Gemini
Sheldon Mills, an executive director at the UK Financial Conduct Authority (FCA), has called for direct regulation of ChatGPT, Claude and Gemini, arguing that language models increasingly shape the financial decisions of British consumers. According to Mills, the existing regulatory framework was built before the era of generative AI and does not protect consumers who get mortgage or investment advice from AI systems.
AI-processed from TNW; edited by Hamidun News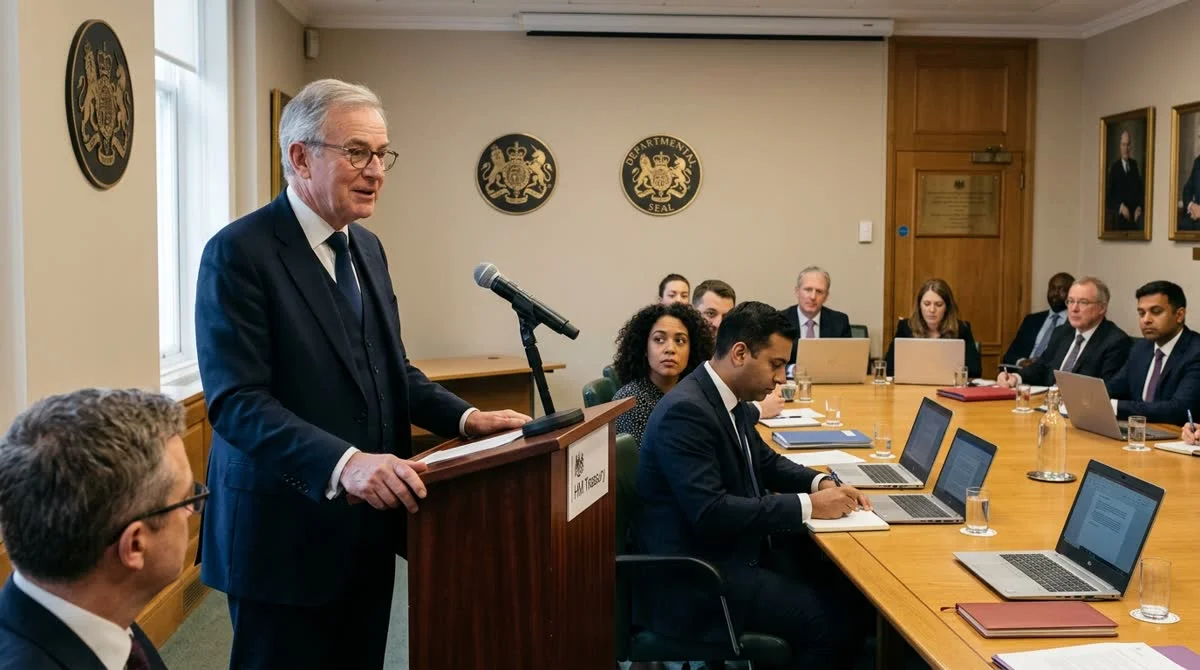
On 7 July 2026, Sheldon Mills, an executive director at the UK Financial Conduct Authority (FCA), urged the country to seriously consider directly regulating large language models: ChatGPT from OpenAI, Claude from Anthropic and Gemini from Google. In his words, these systems have a growing influence on the financial decisions of ordinary consumers, while a regulatory framework created before the arrival of generative AI needs a serious update.
Why a financial regulator is turning to language models
The FCA is the UK's main financial regulator. It licenses and supervises tens of thousands of market participants: banks, insurers, investment platforms and retail brokers. Any organization that gives financial advice to British citizens must meet its requirements.
Mills, who is responsible for competition and consumer protection at the FCA, pointed to a fundamental gap: language models act as financial advisers for millions of people in practice, but not in law, and they fall outside FCA regulation. When a consumer asks ChatGPT whether to take out a mortgage now, or asks Gemini to build an investment portfolio matched to their risk profile, no one is legally responsible for the quality of the answer.
Unlike a bank or a licensed adviser, an AI company is not required to check that a recommendation suits a specific client, disclose conflicts of interest or compensate for harm caused by bad advice. Mills described this imbalance as a problem that calls for a regulatory response.
What would change if the FCA introduced direct regulation
Direct oversight of language models by a financial regulator would set a precedent worldwide. Today the FCA supervises financial products and services, but not technology as such. If the agency extends its oversight to LLMs, Anthropic, OpenAI and Google would come under the direct reach of British financial law for the first time.
Possible consequences for AI companies:
- An obligation to disclose how their models form answers to financial queries
- Warning users that an LLM is not a licensed financial adviser
- Audits of answers for compliance with consumer protection standards
- Restrictions on, or licensing of, personalized investment recommendations
This is not about banning AI in the financial sector, but about extending to it the principles of transparency and accountability that are mandatory for traditional market participants.
Mills stressed that the regulatory framework must evolve as companies rely more and more on AI tools in their work with clients. For comparison, the EU, under the EU AI Act adopted in 2024, has already classified high-risk uses of AI in lending and insurance as requiring enhanced oversight. After Brexit, the UK developed a more flexible regulatory model, and Mills's rhetoric points to a possible shift.
What this means
The fact that a key FCA official raised the question publicly is a significant signal: the debate over direct oversight of LLMs in finance has moved from the academic realm to the practical regulatory agenda. If the UK becomes the first major jurisdiction to introduce specific requirements for language models in financial scenarios, it will set a precedent and put pressure on regulators in the US, the EU and other markets. AI companies whose products are widely used in financial contexts should already be following developments in the British regulatory agenda closely.
- Nov 1, 2026OpenAI Rewrites GPT Behavior Rules: Five Values and a Chain of Command
- Nov 1, 2026Google admits AI Mode cuts search revenue, shares fall 15%
- Oct 31, 2026Author puts his script before an AI jury: the verdict cost 850 thousand tokens
- Oct 31, 2026Anthropic: Fold Subagents Back Into a Single Loop — One Customer's Tasks Ran Twice as Fast
Key Questions Answered
Why a financial regulator is turning to language models?
The FCA is the UK's main financial regulator. It licenses and supervises tens of thousands of market participants: banks, insurers, investment platforms and retail brokers. Any organization that gives financial advice to British citizens must meet its requirements. Mills, who is responsible for competition and consumer protection at the FCA, pointed to a fundamental gap: language models act as financial advisers for millions of people in practice, but not in law, and they fall outside FCA regulation. When a consumer asks ChatGPT whether to take out a mortgage now, or asks G
What would change if the FCA introduced direct regulation?
Direct oversight of language models by a financial regulator would set a precedent worldwide. Today the FCA supervises financial products and services, but not technology as such. If the agency extends its oversight to LLMs, Anthropic, OpenAI and Google would come under the direct reach of British financial law for the first time. Possible consequences for AI companies: An obligation to disclose how their models form answers to financial queries Warning users that an LLM is not a licensed financial adviser Audits of answers for compliance with consumer protection standards
What this means?
The fact that a key FCA official raised the question publicly is a significant signal: the debate over direct oversight of LLMs in finance has moved from the academic realm to the practical regulatory agenda. If the UK becomes the first major jurisdiction to introduce specific requirements for language models in financial scenarios, it will set a precedent and put pressure on regulators in the US, the EU and other markets. AI companies whose products are widely used in financial contexts should already be following developments in the British regulatory agenda closely.
Test Frontier LLMs & Autonomous Agents in One Workspace
Run Claude Opus 5.5, GPT-6, Gemini 3.1, and DeepSeek side-by-side in Nomad AI (nomadnet.ai) — unified model routing, deep research, and multimodal workflows under one subscription.
The AI world, distilled — once a week
Seven stories that actually mattered, hand-picked. No noise, no reposts, no press releases.
Done! Check your inbox for a confirmation.